Subdued mood and diverging markets at EXPO REAL
Developers, investors and financing partners gathered at the Munich trade fair grounds in early October for EXPO REAL. While specialist discussions at the stands and in meeting areas were characteristically constructive, the industry gathering was far from marked by an upbeat sense of renewal. Market participants summed up the situation on site with remarks that 2027 will not be a foregone conclusion and that any tangible recovery in 2028 might come too late for some players.
International property markets are currently moving in distinctly different cycles. While the United States and Spain are already recording positive signals, progress in the German-speaking countries and France remains sluggish. In the Middle East, market conditions continue to be characterised by uncertainty. For the domestic market, this means that persistently high construction costs, demanding financing structures and razor-thin margins will dictate operational business for the foreseeable future.
Leverage in existing stock and serial construction methods
Given the market pressure, value creation is increasingly shifting towards process optimisation, as underlying fundamentals offer little prospect of short-term relief. Losses in profitability typically do not stem from individual major errors, but rather from frictional losses: information reaches project participants late, incomplete or is lost entirely across operational interfaces.
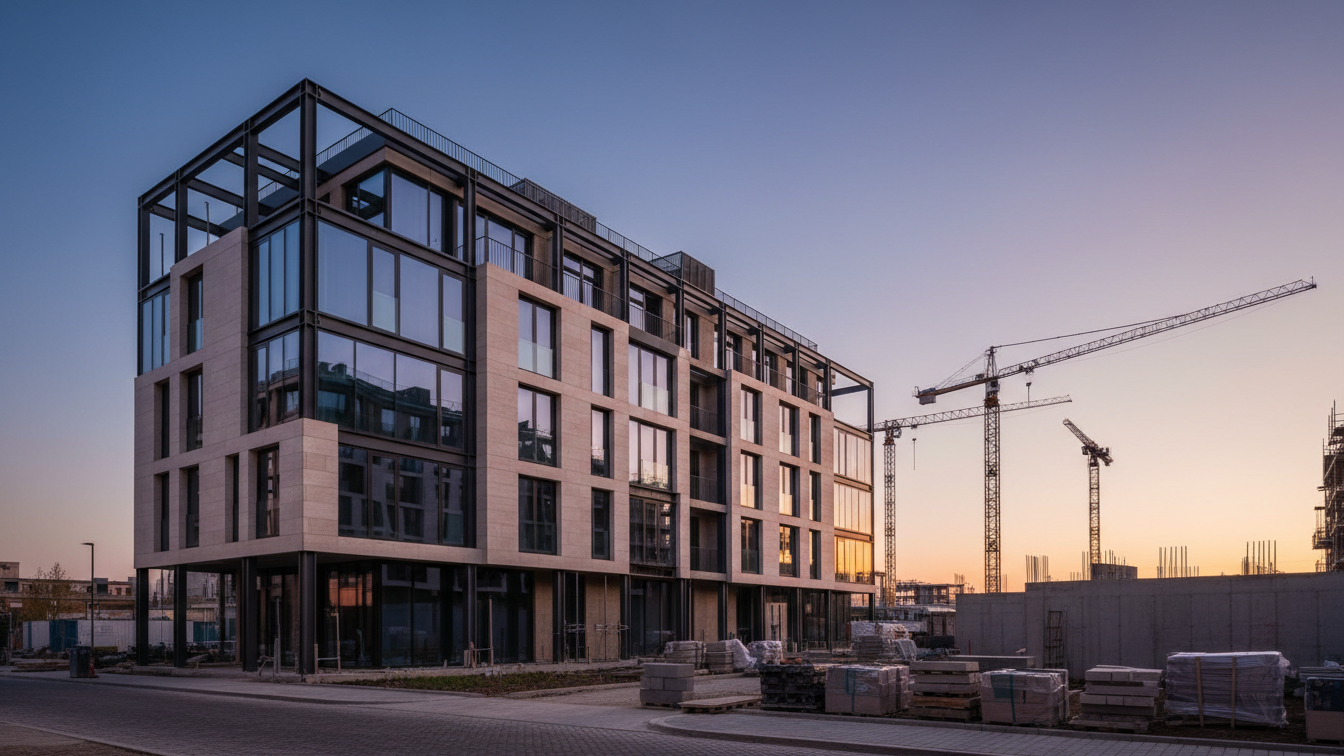
In refurbishments, vertical extensions and conversions, this issue carries considerable weight. Because the actual structural condition of many existing properties is poorly documented, any unforeseen discovery behind wall or ceiling cladding results in costly variations and risk write-downs. Only those who systematically capture existing property data in advance establish the necessary foundation for viable calculations. In the new-build sector, serial and modular construction methods remain the primary viable alternative. However, their cost benefits only materialise in practice if sources of error and recurring delays from previous projects are measurably recorded and eliminated in subsequent contracts.
Segments such as data centres, logistics facilities and energy infrastructure hold a special position, continuing to exhibit considerable market momentum. These assets place high technical demands, where commissioning and handover into live operational management are critical to success:
- —Comprehensive documentation of plant data and operational parameters
- —Complete recording of maintenance intervals and technical inspection records
- —Loss-free information transfer from the construction trades to the FM service provider
Sander van der Rijdt, co-CEO and co-founder of the technology company PlanRadar, does not anticipate a pronounced upturn for 2027, but rather a gradual continuation for those players who have held their ground in the market. He sees the greatest untapped potential in closing information gaps and automating previously manual processes, for example when recording construction sign-offs or documenting warranty defects. With tight margins, precisely these interfaces determine whether a project concludes profitably.